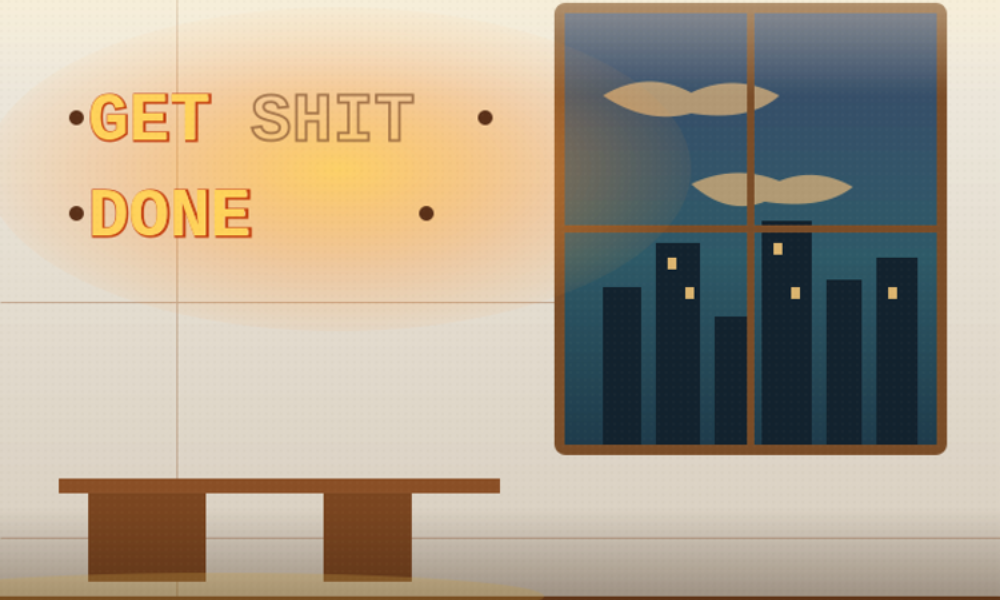
The sign is gone now, but the wall still remembers what it said.
The Missing Word
When Revolut moved into its first office in Canary Wharf, the founders had a mantra installed on the wall in neon: “Get shit done.” The sign is gone now; the office WiFi is called “get it done.” Two words removed, one company changed. Revolut’s most recent share sale valued it at $115bn, more than every UK bank except HSBC. But if you want to understand what the company is actually going through, the missing word tells you more than the valuation does.
How Pirates Are Made
That missing word — the one the sign no longer says — is also the thing that built the speed, and it was there from the start. Nik Storonsky founded the company in 2015, angered by the foreign-exchange fees banks charged travelers, and it won over young customers with a slick app and cheap conversion rates — growing to 80 million customers across 40 countries largely by word of mouth, rather than the advertising spend that built America’s neobanks.
The company’s own systems explain the speed. Where rivals run on “legacy systems and third-party providers that have never been properly integrated,” in Jajodia’s words, Revolut wrote its own. On an owned stack, a new product is a module you bolt on. On a patchwork of legacy systems, it’s an integration problem — reconciling systems that were never built to work together, one by one.
The result looks less like a bank than an everything app — payments as the base layer, with services bolted on, closer to Alipay than to HSBC. Revenue follows the shape: three-quarters of last year’s £4.5bn came from fees — crypto, FX, cards, subscriptions — with net interest income under £1bn. That’s a platform’s income statement, not a bank’s. That’s not a bank’s income statement — it’s a bet that customers will keep coming back for the extras, not the interest.
Hitting the Wall
Wanting to become a real bank meant walking into real regulation. Revolut’s auditor, BDO, delayed signing off its accounts because it couldn’t verify revenue. The UK licence application, filed in 2021, wasn’t approved until March 2026. And last year the European Central Bank restricted Revolut’s growth in Europe after finding “deficiencies” in control and risk functions — the same functions that are meant to govern the company’s breakneck pace of new product launches.
Seen through a technical lens, the hold-up isn’t a sign the technology was bad. It’s a sign the technology was fast. An auditor unable to verify revenue is, in essence, a release cycle that outran its own verification cycle. Product development was outrunning both the accountants booking the revenue and the compliance teams reviewing it. The same speed that gave Revolut its edge gave it its regulatory headache; they are two sides of one thing.
The fixes that followed were organisational, not technical: a British chief executive, an expanded board, a separate management team for the bank, and a wave of compliance and risk hires. Storonsky admitted as much himself, telling guests at the opening of Revolut’s new headquarters that trying to shortcut full banking licences years ago had produced “a worse product.” The admission matters — it’s the founder conceding that regulation isn’t the opposite of the product. It’s part of it.
These fixes were largely structural — more people, more committees. Whether they would hold against a determined trickster was a separate question.
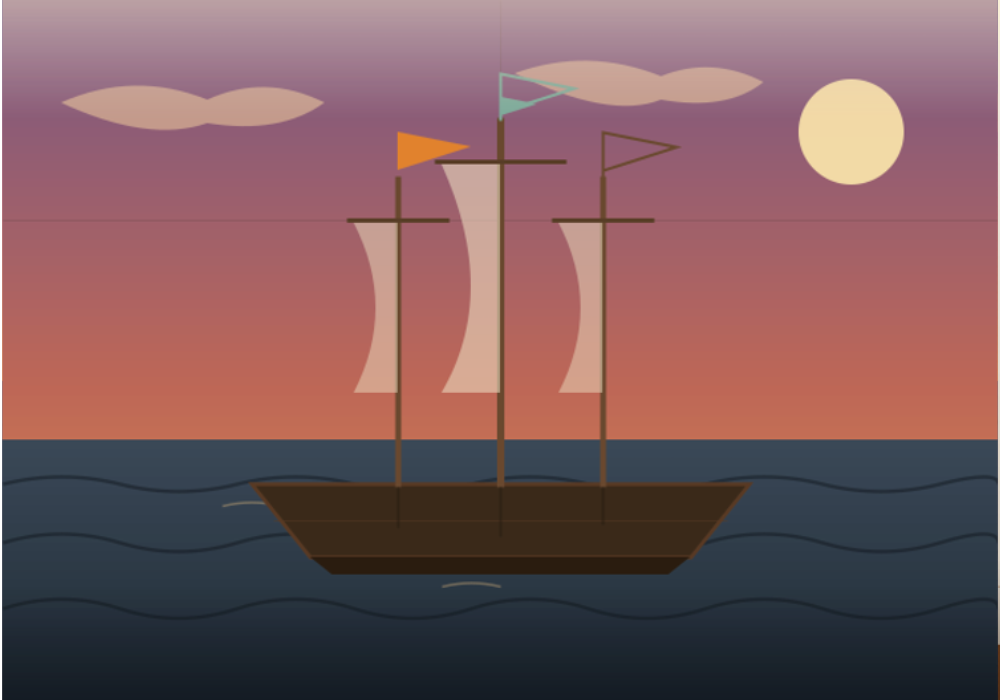
One flag full, one flag half, one flag empty — the same ship, three different results.
Three Tests
One senior person at Revolut, paraphrasing Steve Jobs, put it this way: “You can either operate like a navy or like pirates, and we’re probably more like pirates.” Sid Jajodia, the group’s chief banking officer, went further. Revolut’s speed, he says, comes from technology it owns and controls, not from a lack of scrutiny. It survives three tests.
Test one: On the level of product and platform, the technology totally delivers what Jajodia describes. Revolut’s rivals run on legacy systems and third-party patchwork “never properly integrated,” in Jajodia’s words — while Revolut’s own code lets it ship a new feature the way a company adds a module, not the way a bank rewires five systems at once. Pan-European banks, weighed down by fragmented software, admit as much: one investment banker says they envy Revolut’s “integrated global approach.” Jamie Dimon, JPMorgan’s chief executive, has said the same in blunter terms — he’s “jealous,” he told an investor conference this year, of the upstart. That solves an internal coordination problem. However, it says nothing about what happens once the product is launched.
Test two: On the level of control and fraud, it delivers only half of it. The same rails that move money instantly also move it instantly to the wrong place. Revolut topped the table for fraud complaints to the UK’s Financial Ombudsman Service in both 2024 and the first eight months of 2025 — when customers referred 1,875 cases involving authorised push-payment scams alone — despite its comparatively modest size. In September this year, hackers who spent months posing as an Italian government agency talked Revolut into handing over identity documents and transaction histories on roughly 680 crypto-wealthy customers, then demanded a $3m ransom in cryptocurrency — not its first such lapse, after a 2022 breach exposed more than 50,000. The European Central Bank, restricting Revolut’s growth last year, pointed to the same gap: control functions that hadn’t kept pace with the “breakneck” release of new products. Rules can be written into code. Judgment about a stranger on the other end of a transfer cannot.
Judging fraud is a check on something that already happened. Underwriting a loan is a bet on something that hasn’t.
Test three: On the level of credit, it delivers none of it. Revolut’s loan book grew 120 per cent last year, to £2.2bn from roughly £1bn — still “tiny,” in JPMorgan’s assessment, next to a boutique lender. Building the underwriting capability, credit infrastructure and regulatory capital to scale it, JPMorgan’s analysts wrote, “will probably be a multiyear endeavour.” BNP Paribas’s Ygal El Harrar put it more bluntly: Revolut has grown so far “without having to bear any significant risk.” Storonsky told the FT as much himself: the bank has no plans to let credit exposure rise above 10-20 per cent, with loans sold on or securitised to keep “effectively zero risk for the business.” Jajodia doesn’t dispute the caution — he says the group is now hiring underwriting and credit-risk specialists as it builds the business. A pirate ship, in other words, just hired a navy — and isn’t in a hurry to put it to sea.
Technology ate the parts of banking that could be automated. What’s left — control, underwriting, trust — is more expensive, slower, and depends on people. No clever software can hire them for you.
Two ships, two directions — each sailing into what the other is leaving behind.
Opposite Crossings
Jamie Dimon first met Storonsky in 2019 and doubted Revolut could scale beyond Europe. He’s since changed his mind and admitted JPMorgan has “got to get faster.” One executive at Revolut, meanwhile, says the company’s real comparison isn’t a bank at all — it’s Amazon — and predicts that balancing founder-led dynamism — the same fast, instinctive, “Get shit done” style that built the company — with broader governance will be its biggest challenge. The navy is crossing over into piracy. Meanwhile, the pirates are crossing over into a navy.
That second crossing is going the faster of the two. Revolut is already halfway through it. But the pace isn’t uniform. In September, the US Office of the Comptroller of the Currency gave Revolut conditional approval to organise a national bank — withholding sign-off on four specific services, from retail foreign exchange to correspondent banking, and taking 176 days against the regulator’s own 120-day target. Two months earlier, Australia’s prudential regulator had handed Revolut a full, unrestricted deposit-taking licence outright, the first global fintech to receive one. Same company, same owned tech stack, two different clocks in different jurisdictions. Learning to be a navy, it turns out, isn’t a single exam. It’s a different test in each market. The real question is whether the institutions that always played by the rules can tolerate a sign on the wall that once said “Get shit done” — and how much that tolerance depends on which regulator’s office it’s hanging in.
Three numbers will tell you which future is arriving: the bad-debt ratio on that loan book, the share of customers who trust Revolut enough to make it their main account, and whether the next impersonation scam finds the gap again.
Pirates learning to be a navy is easy. It just costs money. Navies learning to be pirates is harder — it means rewriting the incentives and the tolerance for failure that no hire can bring with them.
Data Source
Reporting for this column draws primarily on the Financial Times investigation “Revolut’s mission to dominate banking” (5 September 2026). Additional details on Revolut’s US and Australian licensing are drawn from public filings and reporting by the US Office of the Comptroller of the Currency, the Australian Prudential Regulation Authority, and Bloomberg. Fraud complaint data is drawn from Financial Ombudsman Service records obtained by consumer group “Which?” through a Freedom of Information request. Details of the September 2026 data breach, including the $3m ransom demand and the scale of customers affected, are drawn from reporting by the Financial Times, Euronews, OCCRP and American Banker; details of the 2022 precedent are drawn from reporting by BleepingComputer. Loan-book figures are drawn from Revolut’s 2025 annual report and reporting by GuruFocus; the 120 per cent growth figure is drawn from independent analysis published on businessmodelanalyst.com. Storonsky’s comments on limiting credit exposure and securitising loans are drawn from a separate Financial Times interview conducted by Patrick Jenkins, published in September 2026.